EXPERTISE
For senior management, procurement performance is measured across five dimensions: the actual impact on the income statement, cash flow, supplier risk management, CSR contribution, and value creation (innovation, quality). An executive dashboard needs no more than 6 to 8 metrics, provided they are linked to financial results and tracked with the same rigor as revenue.
In our article “ Horizon 2035 ,” we described how the procurement function is becoming a strategic lever in the face of supply chain pressures, decarbonization, and cost volatility. One very practical question remains for executives: How can they tell if their procurement efforts are truly delivering results?
What is procurement performance?
Procurement performance refers to the procurement function’s ability to contribute to the company’s objectives: profitability, business continuity, compliance, environmental and social commitments, and differentiation. It is not limited to negotiated savings. There are generally two levels:
- Procurement function performance: the efficiency of the team, processes, and tools (processing times, function costs, expense coverage rate).
- Performance through procurement: a measurable contribution to the company’s results (margin, cash flow, risks, CSR). Senior management is primarily concerned with the second level. The first falls under the operational management of the procurement director.
Why Are Traditional Metrics No Longer Enough?
Many procurement reports show a single figure: “procurement savings.” This figure poses three problems for the executive committee:
- It is often merely declarative: a negotiated savings figure does not equate to realized savings. If volumes change or orders are placed outside the contract, the announced savings do not appear on the income statement (P&L).
- It ignores trade-offs: a price reduction may come with longer supplier payment terms, a risk of dependency, or a decline in quality.
- It is disconnected from emerging challenges: supply chainresilience , Scope 3 emissions, and due diligence—none of which are reflected in a price metric. The challenge, therefore, is to develop a balanced framework that a CEO or CFO can review in five minutes.
The 5 Categories of Metrics to Track in the Executive Committee
01.
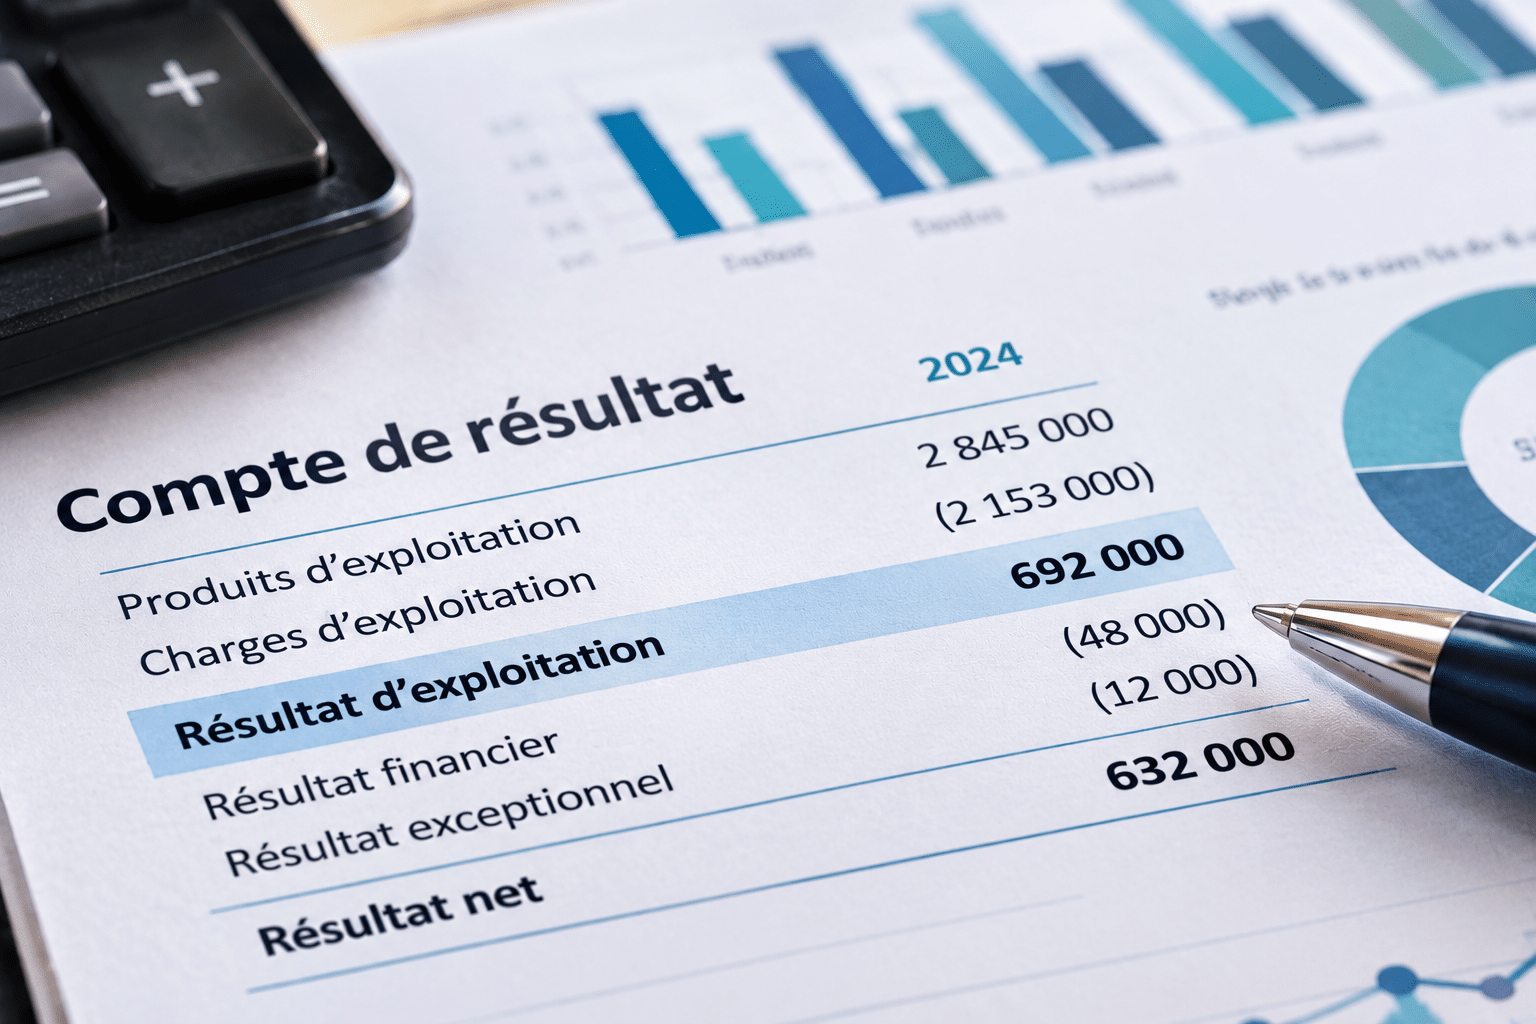
Impact on the Income Statement
- Realized (non-negotiated) procurement savings: the difference between the actual cost recorded and a benchmark shared with the finance department (budget, price from year N-1, market index). The calculation method must be approved by the CFO; otherwise, the figure will not be accepted.
- Total Cost of Ownership (TCO) trends: purchase price + logistics + quality + maintenance + end-of-lifecosts . Essential for equipment and technical categories.
- Price variance vs. market indices: for raw materials or energy, this helps distinguish negotiation performance from cyclical effects.
02.
Cash Flow and Working Capital Requirements
- Average days payable outstanding (DPO) for suppliers must be managed in accordance with French law (the Economic Modernization Act (LME)): 60 days from the invoice date or 45 days from the end of the month, except in special cases. Extending these timeframes beyond these limits exposes the company to penalties and undermines critical suppliers.
- Inventory levels related to procurement: replenishment lead times, batch sizes, safety stock. This is where procurement aligns with the Lean approach.
03.
Supplier Risk Management
- Dependency ratio: the proportionof spending concentrated on a single supplier, or the proportion of a supplier’s revenue generated by your company.
- Percentage of critical suppliers for which a qualified alternative is available (dual sourcing or business continuity plan).
- Supplier service rate: on-time, on-quantity, and on-quality deliveries (complete and on-time deliveries (OTIF)).
- Contractual coverage: the proportion of spending covered by an up-to-date contract.
This category is often the most overlooked, even though it protects revenue. A supplier disruption generally costs far more than just a few percentage points in price.
04.
CSR Contribution
- Percentage of expenditures covered by a supplier CSR assessment ( questionnaire, audit, third-party rating).
- Greenhouse gas emissions related to procurement (upstream Scope 3), at least for the categories with the highest emissions. For companies subject to the European Sustainability Reporting Directive (CSRD), this indicator is now a required element of sustainability reporting.
- Percentage of purchases made from the protected and adapted sector, from SMEs, or from local suppliers, depending on your commitments.
05.
Value Creation and Efficiency
- Supplier contribution to innovation: number of jointly developed projects, percentage of revenue derived from products incorporating a supplier innovation.
- Procurement coverage rate (spend under management): the share of spending actually managed by the procurement function. A low rate indicates “maverick buying.”
- Return on investment for the procurement function: gains realized relative to the function’s costs. Useful for making decisions regarding hiring or tools.
+
Developing a Procurement Dashboard That Is Useful to Senior Management
- Limit the number of metrics: select one or two metrics per category, for a total of 6 to 8. The others should remain under the operational oversight of the procurement department.
- Establish shared calculation rules: Each metric must have a data sheet detailing its definition, data source, frequency, person in charge, and calculation method validated by the finance department. This is essential to ensure that the figures are discussed rather than disputed.
- Adjust the frequency: Realizedsavings , DPO = Monthly | Service rate, critical risks = Monthly or quarterly | CSR, Scope 3, innovation = Semi-annual or annual |
- Link metrics to decisions: A metric that never triggers action is useless. For each one, define an alert threshold and the associated decision: reissuing a request for proposals, qualifying a second source, or developing a supplier development plan.
The Often-Overlooked Link: Skills
Even the best metrics are useless if buyers—and, more broadly, internal decision-makers—don’t know how to gather data for them or make use of them. Calculating TCO, conducting risk analyses, and evaluating CSR: these are skills that can be learned. That’s why we created formations-achats.com, our training organization. There, we offer courses for buyers, managers, and non-buyers.
> On the consulting side, our consultants get involved early on: conducting procurement maturity assessments, building executive dashboards, rolling out performance plans, and aligning them with your Lean and CSR initiatives.
CONCLUSION
For senior management, procurement performance is managed using a concise and balanced framework:
- Income Statement (P&L, for “profit and loss”): realized gains, total cost of ownership (TCO)
- Cash: payment terms, inventory levels
- Risks: supplier dependency, use of dual sourcing, service levels
- Corporate Social Responsibility (CSR): supplier evaluation, indirect greenhouse gas emissions from the value chain (Scope 3)
- Value creation: innovation, expense coverage ratio.
This framework concretely translates the vision “ Horizon 2035 “”: procurement that no longer focuses solely on reducing costs, but that secures and transforms the company.